The world is building airports. Britain is arguing about one.
Britain is not alone in constraining airport growth, but its carbon budgets make the test distinctive. Around the world, expansion reveals how much confidence governments place in aviation’s future decarbonisation.
My wife Sarah works for Britain’s Climate Change Committee.
Recently she was telling me about Heathrow. The government backs a third runway, subject to environmental conditions. Heathrow’s operator wants to build it. And the Climate Change Committee has just concluded that expanding Heathrow would be compatible with the UK’s climate targets only if the government legislates, before granting development consent, to require aviation to cut its emissions and pay to remove whatever remains by 2050. (CCC, 16 September 2026)
That does not mean the industry agrees on the scheme. Major airlines support expansion on condition that it is affordable, while disputing Heathrow’s proposed costs and how they would be paid. Climate compatibility is one hurdle alongside financing and regulatory approval.
At roughly the same time, I kept watching videos from The B1M about airports that made Heathrow look almost quaint, including its films on Dubai’s Al Maktoum expansion and Singapore’s Changi Airport. Dubai is building out Al Maktoum into a five-runway mega-hub. Singapore has started work on Changi Terminal 5. India has built new airports for Delhi and Mumbai. Istanbul opened an enormous new hub in 2018. Hong Kong has just completed a third runway system.
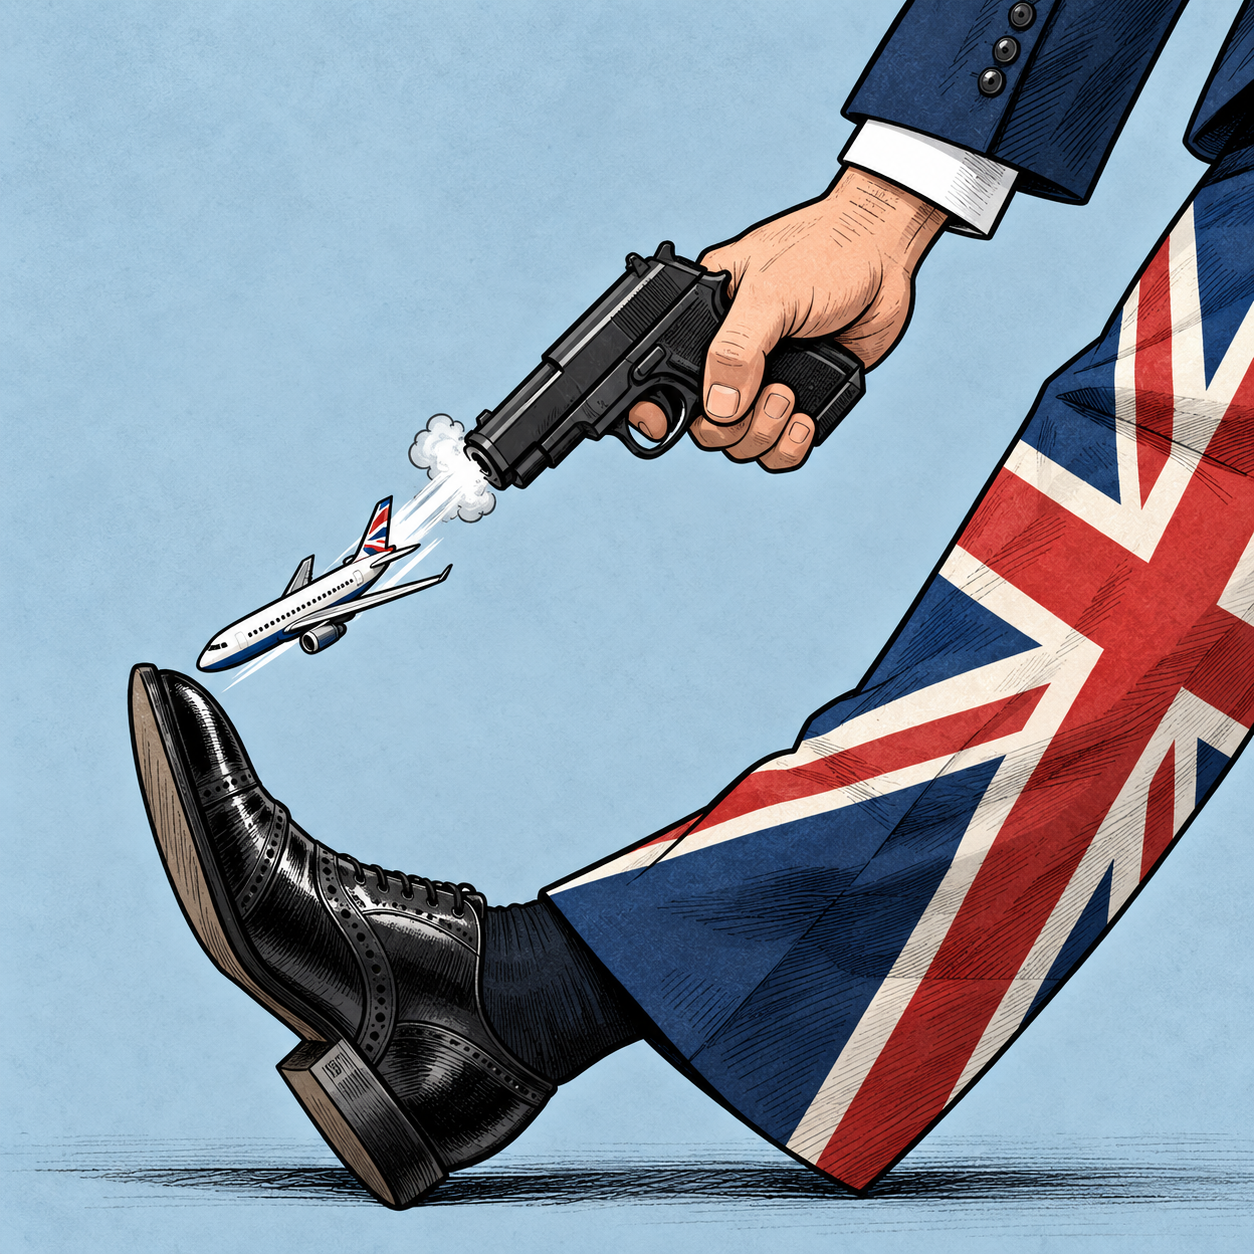
Was Britain shooting itself in the foot over airport expansion? That was the suspicion behind the contrast. The 30-project dataset I built suggested a more interesting answer: other countries also face environmental constraints, and approving capacity often means relying on emissions reductions that have yet to arrive.
Britain is not simply refusing expansion: Gatwick has approval. I have moved the detailed comparison into Why Gatwick’s approval does not settle Heathrow’s case. Here, the question is what distinguishes Britain’s approach from the frameworks used elsewhere.
Is the UK an outlier?
Not in facing the tension between aviation growth and environmental limits. What distinguishes Britain is the framework through which that tension must be resolved. National targets, emissions trading and aviation policies do different jobs; their accounting boundaries and legal force cannot be read straight across from one country to another.
In Britain, the question is not only whether aviation can reach net zero by 2050. The emissions on the way there have to fit inside a sequence of economy-wide carbon budgets. The Sixth Carbon Budget, covering 2033-37, is the first formally to include the UK’s share of international aviation and shipping; the Seventh does too. (UK government)
That makes the emissions consequences a question for the whole economy. If aviation emits more, something else has to emit less, aviation policy has to become tougher, or removals have to make up the difference. But Gatwick shows that deciding whether a project fits still involves forecasts, policy assumptions and ministerial judgement. A binding budget is not a mechanical project-level veto.
France is the clearest counterexample to the idea that only Britain lets environmental concerns stop new capacity. Paris Charles de Gaulle was supposed to get a huge Terminal 4. In 2021 the French government told the airport operator to abandon the project because it no longer matched the country’s environmental ambitions. Paris is now planning substantial modernisation again, but the cancellation matters. Climate policy did not merely require a greener terminal. It helped stop a capacity project.
Austria provides an even stranger case. In 2017 a court rejected Vienna Airport’s proposed third runway partly because of its climate impact. The decision was later overturned by Austria’s Constitutional Court and the runway ultimately survived the legal process. The operator subsequently abandoned the project in November 2025, citing costs, airline opposition and reduced runway-capacity pressure. That makes Vienna less a clean story of climate policy defeating expansion than a demonstration that aviation carbon can become a question on which permission itself turns.
Then there is Amsterdam. Schiphol is still investing heavily in its infrastructure, but Dutch governments have also spent years trying to constrain flight numbers, principally around noise and environmental impacts. The exact cap has moved through litigation and politics. The important point is that the policy argument is about how much aviation the hub should accommodate, not simply how efficient the terminal buildings can become.
These cases establish that Britain has peers in bringing climate or wider environmental limits into capacity decisions. A selected sample cannot tell us how much more restrictive Europe is overall.
But that is only half the result. Europe is still expanding airports too. Frankfurt opened Terminal 3 in April 2026. Madrid is planning a major expansion. Lisbon has selected a site for an entirely new airport that could eventually be enormous. Dublin is trying to raise its passenger cap. Copenhagen is expanding Terminal 3.
The dividing line is not “Europe says no, everyone else says yes”. Even within Europe, the decision frameworks differ.
Singapore shows that a serious commitment to decarbonising aviation can coexist with very large capacity expansion.
You could look at Dubai or Beijing and say that Britain simply has a more ambitious climate regime. Singapore makes that harder. Its Sustainable Air Hub Blueprint explicitly targets net-zero emissions from domestic and international aviation by 2050. A sustainable aviation fuel levy now starts with departures on 1 January 2027, for tickets sold from 1 October 2026. The state is not ignoring aircraft emissions.
It is also building Changi Terminal 5, designed to add roughly 50 million passengers a year in its first phase.
Singapore’s policy is therefore not “aviation growth does not matter for climate”. It is closer to: grow the hub and decarbonise the aviation that uses it. The blueprint describes its approach in almost exactly those terms, balancing environmental sustainability with the competitiveness and continued growth of the air hub.
That is a stated strategy, not evidence that the planned growth and emissions reductions will ultimately be reconciled.
The UK–Singapore contrast is therefore one of institutional requirements, not a clean division between restricting growth and trusting technology. Both can approve expansion while relying on future decarbonisation. Britain brings those assumptions into a legally binding economy-wide budget framework; that does not remove the uncertainty or settle every planning decision.
Australia sits somewhere in between. Western Sydney has gone through a substantial environmental approval process, and Melbourne’s third runway is proceeding under a national net-zero framework. Climate and environmental effects are assessed. They have not functioned like the British carbon-budget test.
North America is similar in another way. The United States adopted a federal aviation decarbonisation goal in 2021, alongside very large airport capital investments. That historical plan is not evidence of an unchanged federal climate commitment today. Much of that investment is terminal redevelopment rather than new runway capacity, which makes the comparison imperfect. But the basic policy architecture still looks more like “decarbonise the sector while modernising and growing the system” than “prove this airport project fits within an economy-wide carbon budget”.
Two questions help separate these promises. Which emissions are covered? A target might stop at airport operations or include aircraft and international aviation. What constrains the decision? It might be an aspiration, a planning consideration or a binding requirement capable of limiting capacity. Our map interprets the evidence about the second question; it is not an official legal classification.
This is different from the GHG Protocol’s Scopes 1, 2 and 3, which describe emissions relative to an organisation: direct emissions, purchased energy and other indirect value-chain emissions. An airline’s fuel burn is its Scope 1; aircraft emissions can sit in an airport operator’s Scope 3. Airport operational net zero often concerns the operator’s Scopes 1 and 2. A national carbon budget is a different accounting and legal framework, not another corporate scope. Neither a broader footprint nor a higher scope number automatically means a stronger constraint on expansion.
The distinction matters because a compatibility assessment can expose assumptions that a headline target leaves unstated. It can also accept them: the existence of an assessment does not tell us how demanding its evidential threshold will be.
The dataset is not a census of every airport project. It is a deliberately mixed sample of 30 major expansions, weighted towards new airports, runways, large hubs and useful rich-country comparisons. For each one I tried to answer a narrower question than “does this country care about climate?”
Did climate policy materially constrain the decision to add airport capacity?
Project types complicate the comparison too. Terminal projects are not the same thing as runways. A replacement concourse at JFK can improve an airport without enabling anything like the capacity jump of a new greenfield airport. The map deliberately shows both because they reveal how different countries talk about airport investment, but the strongest comparisons are runway against runway and new airport against new airport.
Two further limitations matter.
First, airport decisions are path-dependent. Brisbane’s new parallel runway opened in 2020 after a planning process that long pre-dated Australia’s current statutory net-zero framework. Beijing Daxing opened in 2019. Comparing those decisions directly with Heathrow in 2026 would confuse chronology with policy preference. The interactive therefore shows current climate commitments alongside the project status, but the prominence score is based on the role climate played in the capacity decision, not on how ambitious the country looks today.
Second, “environment” is broader than carbon. Schiphol’s constraints are inseparable from noise and local pollution. Vienna’s runway litigation involved a particular legal context. Dublin’s passenger-cap argument includes surface access and planning conditions. The reviewed coding includes broader environmental gating at Schiphol; it should not be read as a climate-only ranking. Its noise constraint is not equivalent to Britain’s carbon-budget test.
The categories are therefore best read as an interpretation of institutional friction. The dataset was assembled with ChatGPT assistance; the classifications are analytical judgements, not ratings issued by the linked sources. The workbook records that analysis but is not independent evidence for it. At one end, climate is something a project must survive. At the other, it is something the airport is expected to manage while the strategic case for expansion is largely taken as given.
I also left unknowns as unknowns. The phrase “net zero by 2050” is easy to find in national plans; whether it explicitly includes international aviation on a comparable accounting basis often is not. The interactive only marks that inclusion as established for the UK and Singapore, supported by the government sources linked above. Elsewhere, “Not established in this review” means inclusion has not been established in this research, not that the country excludes aviation.
The comparison is therefore about what a climate commitment requires of an expansion decision, not which country cares more. The next question is what makes continued growth appear compatible with those commitments.
Why is so much of the world still expanding airports?
Expansion often proceeds on the expectation that aviation can become less emissions-intensive while capacity grows. That is a judgement about future delivery, not necessarily an absence of climate policy. The clearest evidence here comes from the UK’s modelling and Singapore’s stated strategy; it would be a mistake to attribute an identical technological plan to every project on the map.
In the projects reviewed outside Europe, climate commitments commonly accompany capacity growth without a demonstrated UK-style carbon-budget compatibility test. That is a finding about this selected sample, not a global frequency estimate.
In the developing Asian and Gulf projects in this sample, airport capacity is generally framed as strategic infrastructure. Delhi’s new Noida airport, Navi Mumbai, Beijing Daxing, Hong Kong’s third runway system and Istanbul’s mega-airport are responses to congestion, urban growth, tourism, trade and hub competition. Dubai’s ambition for Al Maktoum is on another scale again.
Climate policy is not absent from these projects. New airports advertise efficient buildings, solar power, electric ground vehicles and sustainable design. National governments have net-zero or carbon-neutrality pledges. But in most of the cases I reviewed, I found much less evidence that the emissions from the additional flights were allowed to determine whether the capacity should exist.
Connectivity and climate commitments can therefore sit alongside each other without the latter determining whether capacity is built. Where governments do claim compatibility, the useful question is what is expected to change: fuel use, fuel production, aircraft, demand, or the treatment of residual emissions. The UK provides a particularly explicit account.
The UK’s modelling shows what that reliance on future decarbonisation means. Additional flights continue into later carbon-budget periods; compatibility depends partly on aviation becoming less emissions-intensive. That does not mean long-haul jets become zero-emission. Jet Zero’s 2022 high-ambition scenario assumed 2% annual fuel-efficiency improvement, 50% SAF uptake by 2050 and some zero-emission aircraft, mainly on domestic and short-haul routes. It still left 19.3 million tonnes of annual residual emissions in its illustrative accounting. (DfT analytical annex, pp. 9–10)
Efficiency means burning less fuel through better aircraft, engines and operations. Sustainable aviation fuel, or SAF, still releases CO₂ when burned: its advantage depends on the carbon’s origin and the emissions from making the fuel, not a clean exhaust. Carbon markets are different again. Jet Zero modelled the effect of carbon prices on demand and left residual emissions to be addressed outside aviation; buying an allowance or offset is not itself permanent carbon removal. (Jet Zero Strategy, pp. 16, 48–51; DfT SAF guidance)
Those older ambitions are not today’s policy forecast. DfT’s 2026 Current Trends model assumes roughly 17% SAF by 2050; the CCC’s recommended pathway assumes 38%, slower demand growth and permanent engineered removals to balance residual emissions. The CCC expects novel aircraft to contribute little by 2050, mainly on shorter routes. Its net-zero pathway requires stronger policy, not just delivery of existing measures. (DfT, paragraph 5.137; CCC, chapters 2–3)
Net zero does not mean a zero-emission airliner
For context: London Heathrow → New York JFK, one economy passenger, one way, is about 380 kg direct CO₂ today.
The bars below show the CCC’s UK aviation pathway, not that individual flight. Both use a 100-unit sector baseline for 2050.
2050 without further decarbonisation action · 100 units
2050 recommended pathway · how those 100 units are addressed
- 36 units · residual / removalsStill emitted on the model’s accounting basis; balanced by permanent engineered removals.
- 20 units · SAFLower accounted emissions through alternative fuels, not the disappearance of exhaust CO₂.
- 20 units · efficiencyLess fuel needed through aircraft and operational improvements.
- 24 units · slower demand growthFewer journeys than in the baseline, not a cleaner individual flight.
Residual emissions + equivalent permanent removals = modelled net zero. The aircraft still emit CO₂.
Calculation, accounting and limits
Calculated distance: 5,539.43 km using a great-circle calculation (Earth radius 6,371.0088 km), from the NATS Heathrow reference point and FAA JFK reference point. Multiply by 0.06826 kg CO₂/passenger-km (2026 full-set workbook, “Business travel- air”, J28) = 378.12 kg, rounded to 380. The factor already includes the 8% distance uplift; it is not added twice. This is a fleet-average reporting estimate with economy-seat and freight allocation, not a measurement of a specific flight. The workbook’s CO₂e total and radiative-forcing-adjusted factor are deliberately not used.
Both bars use the same 100-unit sector baseline: 36 units remain and require engineered removals, while SAF avoids 20, efficiency 20 and slower demand growth 24. The 380 kg passenger estimate is separate and is not used to calculate these segments. Avoided journeys are not an emissions saving on a journey still taken. Different aircraft, load factors, fuel mixes and accounting boundaries prevent a defensible route-specific 2050 forecast from these aggregates. The passenger estimate excludes fuel production and non-CO₂ warming: it is not the journey’s full climate footprint.
SAF’s physical exhaust CO₂ is not the same as its lifecycle or national-inventory emissions. Fuel-production emissions may be counted in other sectors. Jet Zero’s annex reports 19.3 MtCO₂e residual emissions in 2050 when using its illustrative SAF savings treatment, but 15.4 MtCO₂e under whole-economy accounting. Neither number measures all physical exhaust CO₂. They must not be mixed with the passenger factor or interpreted as full lifecycle flight footprints.
The CCC split is against a 2050 baseline without further decarbonisation action, not against today’s emissions. Its percentages are rounded and its mix is uncertain. It includes permanent engineered removals; generic offsets or emissions allowances are not equivalent. Non-CO₂ effects such as contrails remain outside these bars, so modelled net-zero greenhouse gases do not establish zero warming from aviation.
The mechanism matters: additional flights remain, while compatibility depends on declining emissions intensity and a way to address the residual. The CCC’s newer advice makes clear that delivering its recommended pathway requires more policy than is currently in place.
That exposes the question behind expansion decisions: how much confidence in future decarbonisation is enough to approve expansion now?
The CCC’s new Heathrow advice makes the consequence explicit. Under current policy, it says, aviation emissions would not fall at all by 2050 even without Heathrow expansion. Its answer is not an unconditional ban on the runway. It says expansion could be compatible with the carbon budgets if government legislates stronger measures that make aviation fully address its residual emissions by 2050, including engineered removals where necessary.
The practical question for Heathrow is what government requires before allowing the additional capacity: which emissions must be addressed, which policies will deliver the reductions, and who pays if the technologies cost more or arrive later than expected.
Gatwick shows that a binding carbon budget can accommodate expansion. Singapore shows that a serious aviation target can accompany hub growth. Neither approval nor a target establishes that the promised reductions will arrive.
A net-zero target tells us where a government says aviation should end up. An expansion decision reveals how much confidence it places in getting there.
Drafting and research were carried out with the help of ChatGPT Astra.